How to set up a company in Dubai: the steps, in the order they happen
Each step depends on the one before it. Settle the activity and the jurisdiction first, and the licence, visas, bank account and tax registrations follow in sequence.
- Author
- Orivion editorial
- Published
- Last reviewed
- Reading time
- 7 min
Written from Orivion's delivery practice.
Why this matters
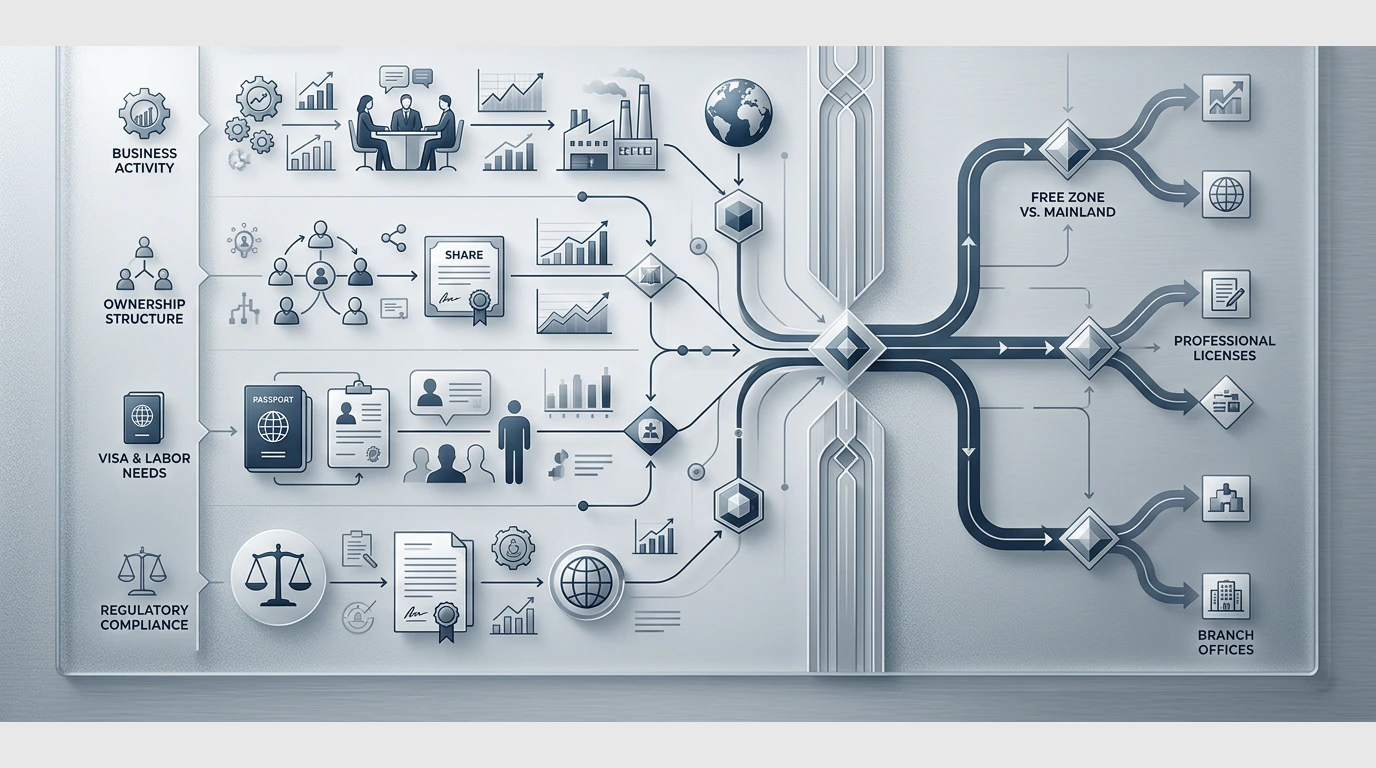
Setting up a company in Dubai is a chain of dependent decisions. The activity decides which licence and jurisdiction fit. The licence decides what the company may do and how many residence visas it can apply for. The bank account and tax registrations then rely on documents produced in the earlier steps.
Most delays come from doing things out of order: choosing a free zone before confirming the activity is permitted there, or approaching a bank before the company file is complete.
Step 1: Define the activity
Start with what the company will actually do and who it will sell to. Licensing authorities issue licences for specific activities, and the activity determines the legal form, any external approvals and whether a mainland or free zone licence suits the business.
Be precise. A loose description often leads to the wrong activity on the licence, and amending activities later costs time and fees.
Step 2: Choose mainland or free zone
Dubai offers mainland and free zone company setup. Mainland companies are licensed by Dubai's Department of Economy and Tourism (DET). Each free zone is run by its own authority, with its own packages, office options and visa allocations.
Mainland usually suits companies that will sell directly to customers across Dubai and the UAE or need local premises. A free zone often suits service, consulting, trading and holding companies. Neither is right by default.
Whether a free zone company can serve customers or carry out activities outside its free zone depends on the activity, the jurisdiction and the applicable licensing and permit framework.
In Dubai, qualifying free zone establishments have routes to carry out activities outside their free zone through DET licences or permits, subject to the applicable conditions.
Foreign investors can fully own onshore companies across many activities. Activities of strategic impact are defined by the Cabinet and carry additional ownership and licensing controls, so ownership must be confirmed for the specific activity.
Step 3: Reserve a trade name and get initial approval
On the mainland, the trade name is reserved with the emirate's economic department, which in Dubai is DET, and initial approval is issued before the remaining documents are submitted. Initial approval lets the application continue. It does not allow the company to start trading.
Free zones run equivalent steps through their own portals. Names are checked against authority rules and existing registrations, so prepare two or three options in order of preference.
Step 4: Prepare the documents and the premises
Depending on the legal form, the company needs a Memorandum of Association or another constitutional document, passport copies for shareholders and managers, and a business address. Mainland companies generally need a registered lease for physical premises.
Where a shareholder is a company, its documents usually need legalisation or attestation in its home country before they are accepted. This is often the longest step, so start it early. Some activities also need approval from another government body before the licence is issued.
Step 5: Licence issue, then the immigration file and visas
Once the licence is issued, the company opens its immigration file, known as the establishment card, before any residence visa application. Each visa then follows its own sequence: entry permit or change of status, medical test, biometrics and Emirates ID.
A visa allocation is capacity to apply for a residence visa. It is not the visa itself, and issuing the visa has its own costs and approvals.
Step 6: Bank account and tax registrations
Banks assess the company's activity, ownership, source of funds and expected transactions. A complete company file and a clear business profile make that review easier. Account opening and approval remain entirely subject to the financial institution's own compliance and onboarding process.
Resident companies incorporated on or after 1 March 2024, including free zone companies, must apply to register for corporate tax within three months of incorporation, establishment or recognition. The administrative penalty for late registration is AED 10,000.
VAT registration is mandatory where taxable supplies and imports exceed AED 375,000 over the relevant period, and may be voluntary above AED 187,500.
Examples
- A consultant serving clients across the GCC on a free zone licence, with one investor visa and a flexi-desk.
- A trading business that needs a Dubai warehouse and sells to local customers, on a mainland licence with a registered lease.
- A foreign company opening a UAE subsidiary, where legalising the parent's documents sets the timeline.
Before you apply
- Write down the exact activities and the customers the company will serve.
- Confirm each activity is permitted in the jurisdiction you are considering.
- Decide the legal form and who the shareholders and managers will be.
- Check whether any activity needs an external approval.
- Start legalising foreign corporate documents early.
- Match the workspace to the number of residence visas you will need.
- Diary the corporate tax registration deadline from the incorporation date.
- Prepare the business profile and source-of-funds documents a bank will ask for.
What to do next
Compare routes in Orivion's UAE Setup Planner, which uses published authority costs, then confirm the shortlist with the authority or an adviser before you apply. Licence, visa and other approvals are decided by the relevant authorities. No outcome can be guaranteed.
Information on this site is general. It is not legal, tax or financial advice. Requirements change, so confirm current rules with the relevant authority or a licensed adviser.
Related articles
Keep reading.
- UAE Market Entry6 min readUAE corporate tax for new companies: rates, registration and deadlinesEvery resident company registers, including free zone companies and those with no tax to pay. The main risks for a new company are deadlines and reliefs, not the rate.Read
- UAE Market Entry6 min readUAE eInvoicing: what changes, when, and what to check nowMandatory electronic invoicing arrives in phases from 2027. It is a data and systems project as much as a compliance one.Read
Want to talk through how this applies to your business?