Industries / FinTech
Digital financial products that move fast without cutting corners on control.
Financial technology companies compete on experience, but they operate under scrutiny. Onboarding, transaction administration, customer data and automation all have to be quick for customers and defensible to regulators, banks and partners. We build the product, data and operational layers with that tension in mind.
Industry challenge
What makes this sector different.
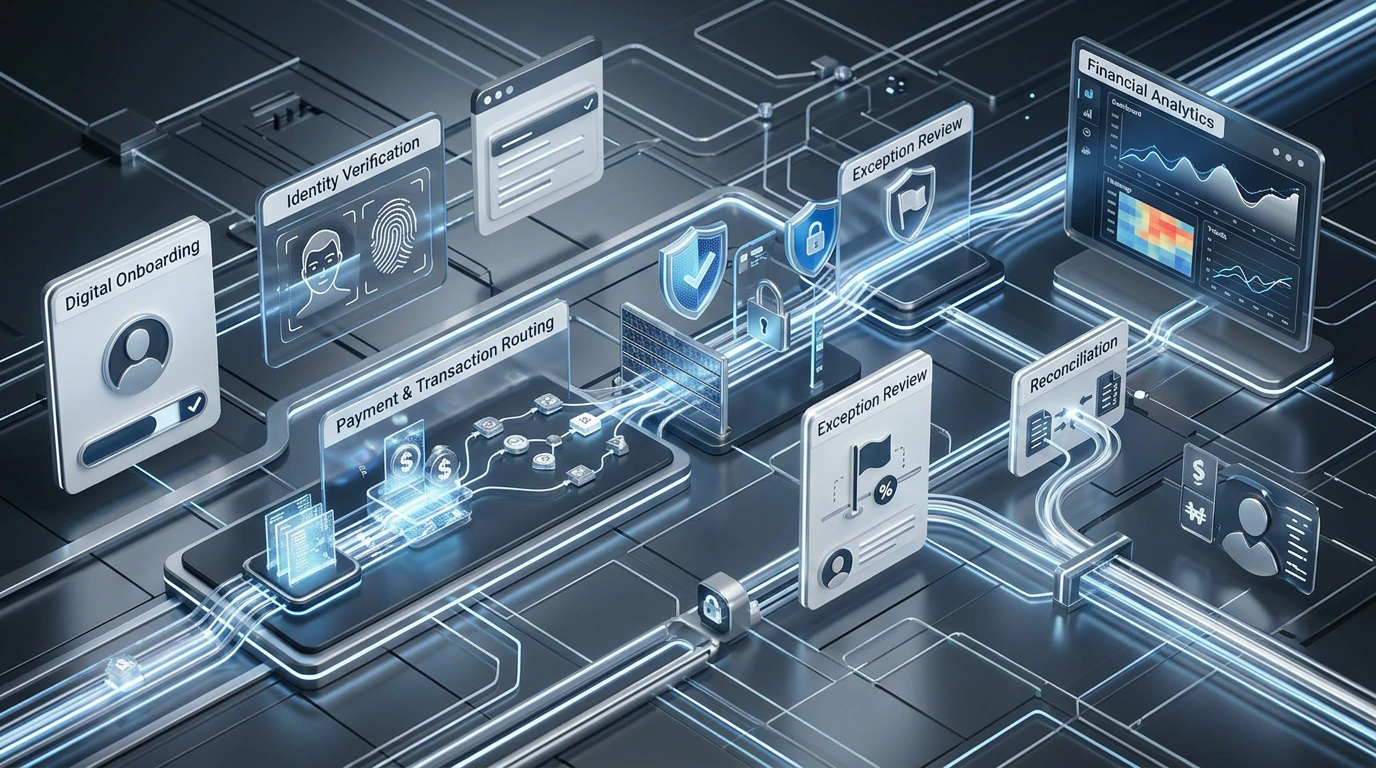
Growth depends on onboarding customers quickly without weakening security or controls.
- 01
Onboarding friction
Identity, documents and checks that are thorough but not abandoned halfway by customers.
- 02
Fragmented operations
Back-office work spread across admin panels, spreadsheets and support inboxes.
- 03
Integration load
Banking partners, payment processors, KYC providers and core systems, each with their own APIs.
- 04
Data under scrutiny
Reporting that must reconcile, with lineage that can be explained.
- 05
Responsible AI
Pressure to use AI, alongside expectations of governance, risk control and cybersecurity.
Digital opportunities
Where digital work pays off.
Digital onboarding
Guided journeys with document capture, validation and clear status for customers and staff.
Operations portal
One internal application for case handling, approvals and audit trails.
Document intelligence
Extraction and classification of documents with human review for exceptions.
Trusted reporting
Reconciled data models and dashboards for management and partners.
Example architecture
Example architecture
A reference pattern, not a specific client system: customer channels on one side, operational and control systems on the other, connected through a governed core.
- Web app
- Mobile app
- Onboarding
- Support
- Notifications
- KYC provider
- Payments
- Case management
- Data platform
- Monitoring
Reference pattern
A connected fintech stack, not a client system.
Channels customers use on one side, operational systems on the other, connected through a governed core. The exact components depend on what you already run.
Use cases
What Orivion builds in this sector.
Customer onboarding flow
Web and mobile onboarding connected to KYC providers, CRM and case management.
Transaction admin platform
Internal tooling for reviewing, approving and correcting transactions with full history.
Customer service with context
Support agents see account status, recent activity and open cases in one place.
Monitoring dashboards
Operational and risk indicators with alerts when thresholds are crossed.
Common workflows
Journeys we connect end to end.
Onboarding
- 01Application
- 02Identity check
- 03Document review
- 04Risk assessment
- 05Approval
- 06Account live
Case handling
- 01Alert or request
- 02Triage
- 03Investigation
- 04Decision
- 05Record
- 06Report
Relevant services
Capabilities that apply here.
- BuildWeb, Apps & Digital ProductsSecure customer-facing web and mobile products.
- BuildSoftware Engineering & CloudAPIs, integrations and internal platforms.
- RunAI & AutomationDocument intelligence and controlled automation.
- RunData & Business IntelligenceReconciled reporting and monitoring.
- RunCRM, Sales & Customer SystemsCustomer lifecycle and service.
Context
Security and regulatory context
Financial services are regulated activities in the UAE and elsewhere. Licensing, data protection, outsourcing and AI governance requirements depend on the regulator and the activity. We design for security and auditability, and work alongside your compliance function and legal advisers rather than in place of them.
International bodies, including the Financial Stability Board, highlight both the opportunities of AI in finance and the importance of governance, risk controls and cybersecurity. Our AI work in this sector follows the same principle: bounded use, measured quality, human accountability.
Information on this site is general. It is not legal, tax or financial advice. Requirements change, so confirm current rules with the relevant authority or a licensed adviser.
Proof
How we would approach it.
Capability demonstrations show how Orivion would approach a problem. They are not client projects and carry no client results.
FAQ
Questions buyers ask
Do you build regulated financial products?
We build the technology. Regulatory permissions, compliance programmes and legal opinions belong to you and your licensed advisers, and we design the systems to support their requirements.
Can you integrate with KYC and payment providers?
Yes, through their APIs, with error handling, logging and reconciliation designed in.
How do you approach AI in financial services?
Narrowly and measurably: specific tasks, evaluated quality, human approval for consequential decisions, full logging and clear accountability.
Insights
Further reading.
- AI & Automation7 min readRules, AI or an agent? Choosing the right kind of automationMost workflows need less AI than the pitch suggests, and more control than the demo shows. A practical way to choose per step.Read
- Data5 min readBefore the dashboard: can the business trust its numbers?Dashboards fail when definitions and data quality are left for later. Start underneath.Read
Working on a fintech challenge? Tell us what needs to change.